SEBON’s New IPO Rules Spark Controversy, Put 90% of Pipeline Companies at Risk
Nepal’s Securities Board (SEBON) has proposed stricter eligibility requirements for companies seeking to issue Initial Public Offerings (IPOs), raising concerns among merchant bankers that the new rules could disqualify 80–90% of nearly 100 companies currently awaiting approval.
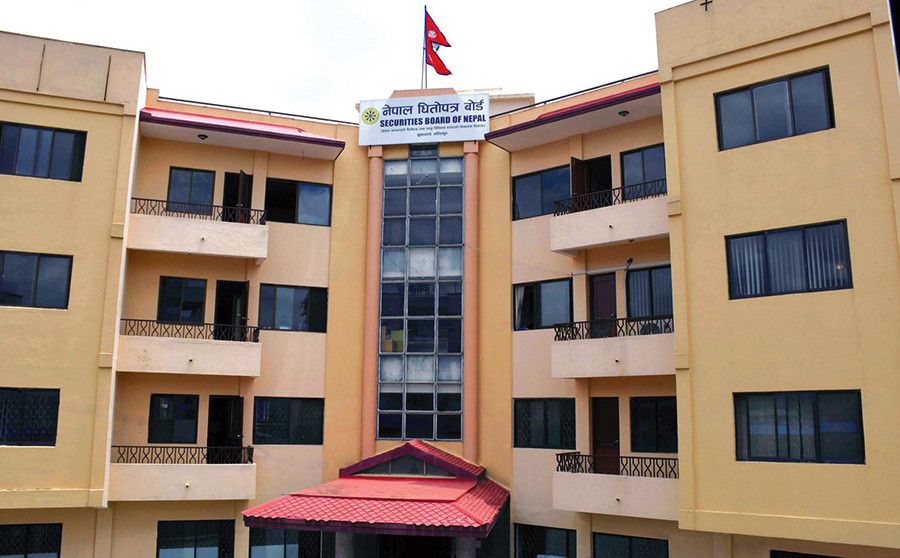
Nepal’s Securities Board (SEBON) has sparked concerns across the capital market with a draft directive aimed at tightening the eligibility criteria for Initial Public Offerings (IPOs). The proposed Directive on General Eligibility for Public Issuance, 2083 has drawn criticism from merchant bankers, who argue that several provisions are excessively restrictive, impractical, and potentially harmful to companies already in the IPO approval pipeline. The most contentious issue is Clause 160, which allows SEBON to apply relevant provisions of the new directive to applications registered before its implementation, if deemed necessary by the board. Merchant bankers argue that this transitional arrangement could unfairly affect companies that have been waiting for approval for two to three years due to regulatory delays. They fear that imposing new requirements on existing applicants would force companies to comply with rules that were not in place when they originally submitted their applications. According to representatives of merchant banks and executives involved in IPO management, implementing the draft directive in its current form could render 80–90% of the nearly 100 companies awaiting IPO approval ineligible. The affected companies span sectors including hydropower, manufacturing, hotels, tourism, and other services. Another major concern involves the corporate governance requirements outlined in Clauses 25 and 26. The draft proposes that companies establish multiple board-level committees, including audit, risk management, nomination and remuneration, human resources, project management and monitoring, and project oversight committees. It also requires companies to appoint a Chief Executive Officer (CEO), Chief Financial Officer (CFO), company secretary, and compliance officer, supported by written policies governing their qualifications and performance. Merchant bankers contend that such extensive governance structures may be suitable for large financial institutions but are unnecessarily burdensome for newly established public companies, particularly those in the hydropower and manufacturing sectors. They argue that requiring smaller companies to maintain numerous committees and specialized personnel would significantly increase administrative costs without necessarily improving practical governance. The proposed financial eligibility criteria have also raised concerns. Clause 16 requires a company's net worth per share to be at least equal to its face value. For companies with a face value of Rs. 100 per share, this would mean maintaining a minimum net worth of Rs. 100 per share. However, capital-intensive businesses, including hydropower projects, cement manufacturers, and steel industries, often experience lower net worth during their initial years because of construction-period interest expenses, depreciation, and early operating losses. Merchant bankers warn that the requirement could prevent such businesses from raising equity capital through the stock market even when their long-term prospects remain viable. The draft also introduces additional compliance obligations, including disaster recovery plans, business continuity plans, cybersecurity audits, and fit-and-proper declarations for founders and directors. Industry representatives fear that the combined requirements could make the IPO process increasingly complicated and time-consuming. While acknowledging the importance of stronger corporate governance, transparency, and investor protection, merchant bankers argue that SEBON should adopt a more practical and sector-sensitive approach. They have called on the regulator to expedite the applications already in the pipeline and clearly communicate the specific shortcomings preventing individual companies from receiving approval. They further suggest that stricter eligibility requirements could be introduced prospectively for new applicants, while existing applications should be assessed under a fair and clearly defined transitional framework. SEBON is currently seeking feedback from stakeholders on the draft directive. Market participants warn that implementing the proposed provisions without addressing industry concerns could delay IPO approvals, discourage companies in the real sector from entering the capital market, and restrict the flow of new investment opportunities for investors. The final impact will depend on how the board incorporates stakeholder feedback into the directive before its implementation.