Skip to content
|Loading...
Share Gyan home
EBook

Monetary Policy Review: NRB Warns of Inflationary Risks as Fuel Costs Soar

Nepal Rastra Bank has left its key policy rates unchanged in its latest quarterly review. While keeping an accommodative stance to spur private sector credit, the central bank announced plans to fine-tune its standing deposit facility to make market interest rates more stable.

Published By Share Gyan
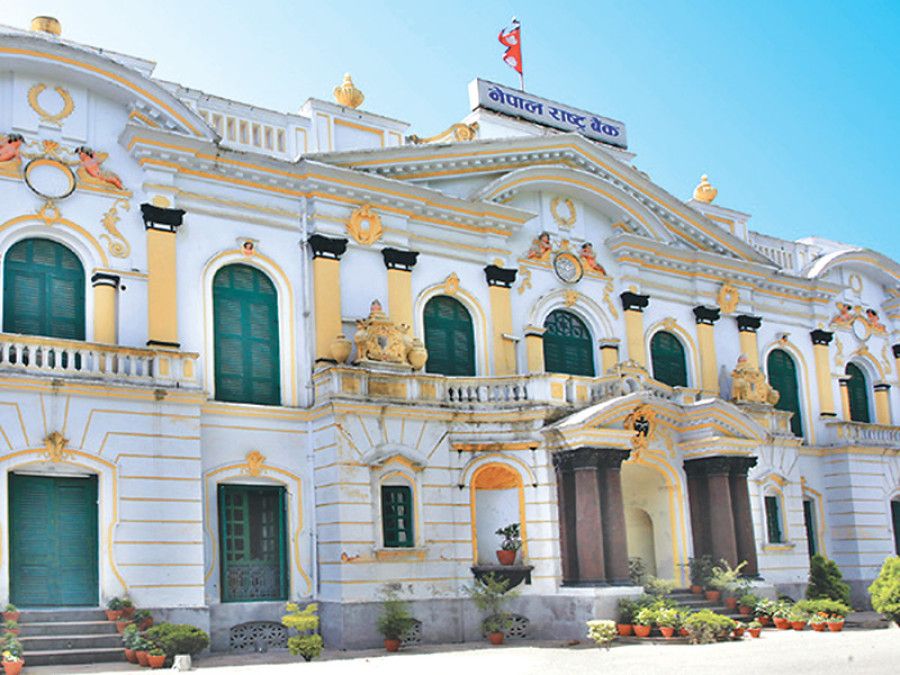
Monetary Policy Review: NRB Warns of Inflationary Risks as Fuel Costs Soar

Nepal Rastra Bank (NRB) has published its Third Quarterly Monetary Policy Review for Fiscal Year 2025/26, signaling a continuation of its flexible and accommodative policy stance to bolster economic growth. According to the central bank's nine-month macroeconomic assessment, the country's financial sector remains highly stable, supported by manageable inflation at 4.47%, a staggering 39.1% surge in remittance inflows, and foreign currency reserves sufficient to sustain 18.4 months of imports. Adopting the National Statistics Office's projected GDP growth rate of 3.85%, the review notes that while the industrial and service sectors are expected to expand by 5.77% and 4.21% respectively, adverse weather has stifled agricultural contribution to a mere 1.58%. Despite these stable undercurrents, the central bank issued a stark warning regarding escalating geopolitical conflicts in the Middle East. External supply chain disruptions have already driven domestic petrol prices up by 35% and diesel prices by 58% during the review period, introducing severe impending inflationary pressures. While the NRB is closely monitoring the potential risks this conflict poses to Nepali migrant workers and future remittance pipelines, it expressed confidence that reserves will remain within target. Consequently, key regulatory levers—including the interest rate corridor, bank rate, cash reserve ratio (CRR), and statutory liquidity ratio (SLR)—will remain unchanged, though the central bank intends to review the standing deposit facility to optimize interest rate corridor effectiveness.

SEBON Approves 50% Right Share Issuance of NIC Asia Bank Worth Rs 7.45 Billion

The Securities Board of Nepal (SEBON) has granted preliminary approval to NIC Asia Bank Limited to issue 50 percent right shares at a 1:0.50 ratio. The bank will issue 74,587,835 shares worth Rs 7.45 billion at a face value of Rs 100 per share.

NRB to Sell Gold Coins and Silver Medallions for Tihar from November 5

Nepal Rastra Bank (NRB) will sell 2.5-gram gold coins and 10-gram silver medallions featuring Goddess Laxmi and Lord Ganesh on November 5 and 6 (Kartik 19 and 20) from its Minting Division in Babarmahal, Kathmandu.

Himalayan Laghubitta Proposes 5% Dividend for FY 2082/83

Himalayan Laghubitta (HLBSL) has proposed a 5% dividend for shareholders, comprising 4.75% bonus shares and 0.25% cash dividend for the fiscal year 2082/83.

Rastriya Banijya Bank Reports 175.52% Growth in Q1 Net Profit

Rastriya Banijya Bank Limited has reported a remarkable 175.52% year-on-year growth in net profit, earning Rs. 1.64 billion in the first quarter of FY 2083/84, compared to Rs. 598.73 million in the corresponding period of the previous fiscal year. The significant growth was driven by a sharp increase in net interest income and a substantial decline in impairment charges.

Kumari Bank Reports Rs. 1.07 Arba Net Profit in Q1; Operating Profit Jumps 32.39%

Kumari Bank Limited (KBL) has reported a modest 1.70% year-on-year growth in net profit, earning Rs. 1.07 billion in the first quarter of FY 2083/84, compared to Rs. 1.06 billion in the corresponding period last fiscal year. Despite a decline in net interest income, the bank recorded strong growth in operating profit, supported by a significant reduction in impairment charges and operating expenses.

NMB Bank Reports 27.11% Growth in First-Quarter Net Profit

NMB Bank Limited has reported a 27.11% year-on-year increase in net profit, earning Rs. 1.16 billion in the first quarter of FY 2083/84, compared to Rs. 915.98 million in the corresponding period of the previous fiscal year. The growth was supported by higher operating income, increased net interest income, and a significant decline in impairment charges.